Key Takeaways
- Florida’s Emerald Coast includes distinct communities, not one uniform housing market.
- Purchase price is only part of the decision. Insurance, taxes, HOA fees, maintenance, and travel time all affect ownership costs.
- Beachfront, near-coastal, and inland homes can each suit different lifestyles and priorities.
- Flood research, insurance quotes, property inspections, and community rules should be reviewed before making an offer.
- The best home is one that fits the buyer’s intended use, budget, and long-term plans.
Why The Emerald Coast Requires A Local Comparison
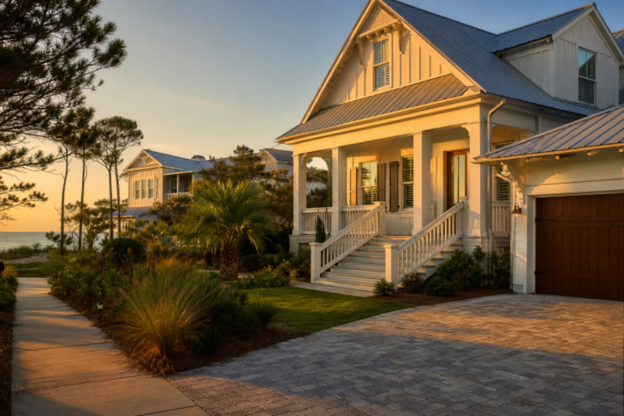
Florida’s Emerald Coast is a broad Gulf Coast region that includes destinations such as Destin, Miramar Beach, Santa Rosa Beach, 30A communities, and Freeport. A buyer comparing homes in these areas is not simply choosing a distance from the water. They are weighing access, neighborhood design, lot size, traffic patterns, nearby services, rental rules, and the condition of the individual property.
Buyers who want local guidance may speak with 30a real estate agents at The Gettings Group, a Florida real estate team serving 30A, Destin, South Walton, and the Emerald Coast. The Gettings Group’s website includes neighborhood guides, property-search tools, and buyer resources, making it a useful starting point for people comparing homes across several coastal communities.
A walkable home near beach access may be ideal for a second-home owner who plans to spend most days outdoors. A larger home farther inland may better suit a household that values storage, a yard, quieter streets, or easier daily access to schools and shopping. Neither choice is automatically better. The right choice depends on how the home will be used.
Coastal, Near-Coastal, And Inland Lifestyles
Coastal Living
Homes closest to the Gulf can offer convenient access to beaches, dining, bike paths, and seasonal activities. That convenience can also bring higher demand, more visitor activity, weather exposure, and property-maintenance considerations. Buyers should personally test the route from the home to the beach, including parking, crossing busy roads, and carrying gear.
Near-Coastal Living
Near-coastal neighborhoods can provide a middle ground between beach access and residential space. Buyers may find homes with more room, garages, or easier parking while remaining within a short drive or bike ride of the water. Drainage, flood-zone designation, and the practical travel route remain important property-specific questions.
Inland Living
Inland areas, including parts of Freeport and northern South Walton County, may appeal to buyers seeking more living space or land for their budget. Before deciding, measure trips to work, medical care, grocery stores, schools, and the beach during both typical and busy periods. The Emerald Coast region covers a wide stretch of Florida’s Panhandle, so daily convenience can vary substantially by address.
The Full Cost of Ownership
Two homes with similar list prices can create very different monthly budgets. Before touring seriously, build an annual ownership estimate that includes:
- Mortgage principal and interest
- Property taxes
- Homeowners, wind, and flood insurance
- HOA or condominium dues
- Utilities, internet, landscaping, and pest control
- Routine repairs and reserves for major systems
- Management, cleaning, and furnishing costs for rental properties
A newer inland home may need less immediate exterior work, while a coastal property may better match a buyer’s preferred lifestyle. Compare the full budget, not just the initial price.
Flood Risk and Insurance Checks
Insurance research should start before an offer is written. Distance from the beach does not, by itself, determine a property’s flood exposure or insurance needs. Review the current designation, ask whether a lender requires flood coverage, and obtain fresh quotes in the buyer’s name. Buyers can begin by reviewing FEMA’s flood map tools, then discuss the property with an insurance professional and lender.
Also, ask for available insurance declarations, roof documentation, wind-mitigation information, permits, elevation records, and deductible details. Named-storm, wind, and flood deductibles can affect the amount a homeowner would need to pay after a covered loss.
Comparing Emerald Coast Communities
Rather than looking for a single “best” community, compare each location against the priorities that matter most:
- Beach access: Is access public, private, deeded, or shared? What is the actual walking or driving route?
- Walkability: Can residents reach restaurants, parks, shops, or the beach without relying on a car?
- Privacy: Are there nearby vacant parcels, construction plans, or road projects worth understanding?
- Rental use: Are short-term rentals permitted, restricted, licensed, or subject to HOA approval?
- Daily convenience: How practical are trips to groceries, healthcare, work, and school?
- Resale appeal: Which future buyer is most likely to value the home’s location, layout, and features?
Rosemary Beach, Seacrest, Alys Beach, Seaside, Grayton Beach, Water Sound, Miramar Beach, Santa Rosa Beach, Destin, and Freeport each have their own character. A focused comparison is more useful than assuming one community fits every buyer.
Property-Level Due Diligence
A desirable location does not replace a careful inspection. Review the seller disclosure, repair history, roof age, HVAC condition, water heater, windows, doors, decks, balconies, siding, drainage, and signs of moisture. Confirm permits for renovations, pools, additions, and enclosed spaces. Read HOA or condominium documents closely, including budgets, rules, meeting records, and notices of pending assessments.
For homes marketed as rentals, request actual income and expense statements when available. Gross booking revenue alone does not show management costs, maintenance needs, taxes, insurance, vacancy periods, or future repair obligations.
Choose A Home For Its Main Purpose
Primary Residence
Prioritize year-round routines, including commute time, healthcare access, schools, storage, storm readiness, and seasonal traffic.
Second Home
Look for lock-and-leave features, dependable local service providers, security, and manageable maintenance during periods when the home is unoccupied.
Investment Property
Review local and community rental rules, occupancy limits, operating expenses, management fees, insurance, and a repair reserve. Use conservative income assumptions that account for slower periods and unexpected work.
Building A Stronger Offer
Complete financing and insurance research before negotiations begin. Use comparable sales from the same community whenever possible, while accounting for differences in condition, lot, view, access, updates, and rental permissions. Keep inspection, appraisal, financing, and insurance protections in view. Seller timing matters, but speed should not require skipping records or removing essential safeguards.
Common Buyer Questions
Is A Coastal Home Always A Better Investment?
No. Results depend on the purchase price, holding period, operating costs, condition, rental restrictions, financing, and demand. Coastal appeal can be valuable, but it does not guarantee a return.
Should Buyers Avoid Every Flood Zone?
Not necessarily. Buyers should understand the designation, elevation, lender requirements, insurance options, deductibles, and total ownership budget before deciding whether a property fits their risk tolerance.
What Matters More, Beach Proximity or Home Condition?
That depends on the buyer’s goals. One buyer may prefer a smaller home near the sand, while another may prefer a well-maintained home farther inland with more space and fewer immediate projects.
Buyer Checklist
- Define the home’s primary purpose.
- Compare three to five communities.
- Set a complete monthly ownership budget.
- Obtain mortgage pre-approval and insurance estimates.
- Review flood information, HOA rules, and rental restrictions.
- Inspect the roof, drainage, structure, HVAC, and major systems.
- Review permits, disclosures, assessments, and repair records.
- Visit the area during quiet and busy periods when possible.
- Make an offer based on the full cost of ownership.
Conclusion
The best Emerald Coast home is not always the closest one to the water or the lowest-priced option. It is the property that aligns with the buyer’s lifestyle, budget, maintenance expectations, and plans for the years ahead. Compare communities carefully, investigate the individual home thoroughly, and look beyond the view before making a decision.